

Instant Cash Advance analysis by Appwee
Borrowing money is already a stressful task, so the way a cash-advance app presents information matters almost as much as the application itself. I approached Instant Cash Advance from that angle: not just whether it promises quick access to funds, but whether a person can move through the experience calmly, read what is being requested, and understand the decision before committing. It is a free finance app from Janssen Herman, aimed at people looking for short-term borrowing rather than long-term budgeting or investment management.
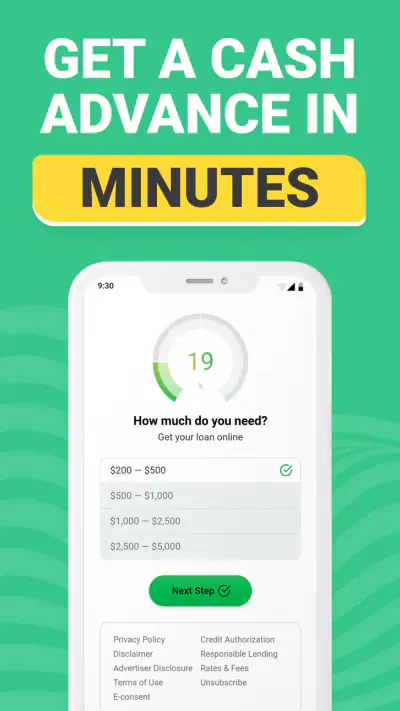
The app’s store summary focuses on fast funds and an instant cash advance, while its shorter description keeps the promise even simpler. That direct positioning is useful because you know immediately what kind of tool you are opening. It is not trying to be a full bank replacement. My overall impression is that it may suit someone who needs to investigate a small, urgent borrowing option quickly, provided they are willing to slow down and examine every term instead of treating speed as the main benefit.
How the app feels to read and navigate
The first accessibility question for a finance app is whether its information can be understood without rushing. In my experience, a cash-advance workflow should be judged by the order in which it presents choices: the amount, repayment expectations, eligibility questions, and any cost-related information need to be easy to distinguish. A simple layout can help, but simplicity is only valuable when it does not hide important details behind hurried taps.
Instant Cash Advance has a very focused purpose, which is an advantage for people who do not want to navigate through savings charts, card controls, investment pages, or unrelated banking tools. A narrow purpose can reduce cognitive load. If you are already worried about an overdue bill or an unexpected expense, opening a dedicated cash-advance app may feel less overwhelming than searching through a large financial super-app.
That focus also creates a responsibility for the user. I would not treat the first prominent action as an automatic recommendation. I would read each screen from top to bottom, look for the full meaning of every request, and pause before submitting personal or financial information. A fast interface is not necessarily a clear interface, especially when the subject is borrowing.
For readers who use larger text or display scaling on their phone, the practical test is whether labels remain complete and whether buttons stay separated when text becomes larger. I cannot responsibly promise that every screen behaves perfectly under every device setting, so I recommend checking the opening flow with your preferred text size before relying on it during an emergency. If a label becomes clipped, crowded, or difficult to distinguish, that is a strong reason to switch to a provider with more comfortable presentation.
The app is rated for Everyone, which makes its intended audience broad, but an age label should not be confused with a guarantee that every person will find the financial process equally easy. Someone with limited financial experience may need more explanation than a short prompt provides. I would keep a note-taking app, calculator, or paper nearby and write down the amount requested, the repayment obligation, and the date involved before confirming anything.
Useful habits for a clearer application process
One of the most practical ways to reduce mistakes is to use the app when you are least distracted. Do not begin while walking, travelling through a noisy station, or trying to solve several problems at once. Read one screen at a time, and take a screenshot or written note only when doing so does not expose sensitive information. The goal is to create a record of what you understood, not to collect private data carelessly.
I also recommend checking that the phone’s screen timeout will not interrupt you halfway through a form. If the session expires, restarting under pressure can lead to repeated entries or skipped reading. A stable connection and a charged phone are equally sensible preparations, particularly when the reason for using the app is urgent. These are small details, but they matter more in a finance workflow than they would in a casual entertainment app.
Another overlooked trade-off is the difference between a short process and an informative process. Fewer screens may save time, yet they may also leave less room for definitions and reminders. If Instant Cash Advance moves quickly, I would compensate by being deliberately slow as a reader. That is not a criticism of speed itself; it is a reminder that the user should control the pace when the outcome affects future income.
Motor, sensory, and situational considerations
People interact with phones in very different ways. A user with limited fine-motor control may prefer large, well-spaced controls and a workflow that does not require repeated precision taps. Someone with tremors, hand pain, or one-handed use may find a long form tiring even if every individual action seems simple. Because borrowing applications can involve sensitive entries, accidental taps are more serious than they would be in a music or weather app.
My advice is to use the app in portrait or landscape mode according to whichever gives you the clearest reach and the least visual crowding. If your device supports system-level magnification, voice input, switch access, or an external keyboard, those tools may make text entry more manageable. I would test them on non-sensitive parts of the workflow first, then verify every automatically entered field before moving forward.
Voice input deserves particular care. It can help a person who struggles with typing, but spoken financial information may be overheard in a shared home, workplace, vehicle, or public space. Accessibility and privacy sometimes pull in opposite directions. A quieter room, headphones, or manual entry may be preferable when the information is personal. The most convenient input method is not always the safest one.
For users with low vision or color-vision differences, I would avoid relying on color alone to understand whether a step is complete or whether an option is selected. Read the accompanying text and confirm the actual action. If contrast, font weight, or spacing makes the screen tiring, increase the phone’s display settings before beginning. A finance app should be comfortable to inspect, because skimming is exactly what I would want to avoid when considering a cash advance.
People with hearing loss may find a purely visual workflow easier than one that depends on sound, but any important alert still needs to be visible long enough to notice. Conversely, users with attention-related difficulties may benefit from turning off unrelated notifications before starting. A message from another app can break concentration at the exact moment a repayment detail needs to be read.
When the surrounding situation changes the experience
Imagine a realistic evening scenario: your phone bill is due, your regular income arrives soon, and you are considering a cash advance to bridge the gap. The app’s focused purpose could make it quicker to investigate than a traditional bank call, especially if you are already comfortable completing forms on a phone. But the same urgency can make the experience less accessible. Stress narrows attention, encourages impulsive decisions, and makes unfamiliar financial language harder to process.
In that situation, I would first calculate whether the upcoming income can cover both the original shortfall and the repayment obligation. I would then use Instant Cash Advance to review the available path, not to assume that approval or speed automatically makes the choice affordable. If the terms are difficult to read, the process asks for information you are not prepared to share, or you cannot confidently explain when repayment would occur, stop and seek a clearer alternative.
The app may also be useful for someone who has limited access to a branch or who cannot make a phone call during working hours. That is a meaningful situational advantage for people in remote areas, people with communication difficulties, or anyone whose schedule makes traditional services inconvenient. Still, digital access depends on a working smartphone, enough battery, a usable connection, and the ability to complete the process privately. Those conditions should be treated as part of the real cost of convenience.
Travelling is another context where caution matters. A person may be tempted to apply from an airport, hotel lobby, or shared rental because an expense appeared unexpectedly. Public Wi-Fi, unfamiliar surroundings, and divided attention are poor companions for a financial application. I would wait for a trusted connection and private space whenever possible. If the need is immediate, I would at least verify the network and avoid saving sensitive information on a shared device.
Where the inclusive experience still has limits
The biggest barrier is not necessarily a button or font. It is the nature of short-term borrowing itself. People who have difficulty understanding repayment schedules, fees, or financial consequences may be placed at a disadvantage by any app that emphasizes immediacy. A clean interface cannot replace plain explanations. If you need a counselor, a branch employee, or a trusted person to talk through the decision, a conventional service may be more suitable than a self-directed cash-advance tool.
There is also a privacy barrier for users who depend on assistance. A trusted helper may need to read the screen or guide the applicant, but sharing a phone during a financial process can expose personal details. I would avoid handing over the device casually, use the operating system’s privacy controls, and keep the final review in the applicant’s own hands. Assistance should improve understanding without transferring control of the decision.
People with limited English literacy, dyslexia, or memory difficulties may need more time than a quick application flow seems to encourage. Reading aloud, enlarging the display, and breaking the process into written checkpoints can help, but those workarounds require effort from the user. If the wording remains confusing after that, I would choose a service that offers clearer human support rather than guessing.
Users should also remember that an app’s popularity does not prove that it is right for an individual situation. Instant Cash Advance has an average rating of 4.6 from around 1.9 thousand ratings, and it has passed 10 thousand installs. Those figures suggest that other people have tried it, but they cannot tell me whether the repayment terms fit my income, whether the workflow suits my accessibility needs, or whether the app is the best option for a particular emergency.
The app was released on August 17, 2023, and the current version is 1.7.4. It supports Android 6.0 and later, which covers a wide range of older devices. That can help people who cannot afford a recent phone, although older hardware may still affect performance, screen scaling, keyboard behavior, or compatibility with modern accessibility tools. Before depending on it, I would install it on the actual device I plan to use and complete the early steps without submitting an application.
Compared with a traditional bank, this app may feel more immediate and less dependent on branch hours, but a bank can offer established support channels and a broader view of your finances. Compared with a budgeting app, it addresses an immediate borrowing need rather than helping prevent the next shortfall. Compared with a credit card or overdraft, the important differences are likely to be the specific terms and repayment structure, so I would compare the total obligation rather than choosing based on speed alone.
That comparison is especially important for repeat use. A cash advance can solve one timing problem while creating another if it becomes part of a cycle. I would consider this app for a clearly defined, temporary gap with a realistic repayment plan. I would not use it as a substitute for regular income, debt counseling, or a sustainable monthly budget. If the same emergency keeps returning, a different financial conversation is needed.
My inclusive verdict
I see Instant Cash Advance as a narrowly focused finance app that may be convenient for a person who wants to explore short-term funds from a phone. Its free price and focused purpose lower the initial barrier to trying it, and its Android support reaches people using older devices. Janssen Herman is the listed developer, and the app’s Everyone rating makes its intended audience broad. Those points make it approachable, but they do not remove the need for careful reading.
For accessibility, my verdict is conditional rather than absolute. The app can fit users who are comfortable with self-service forms, can adjust their phone’s display or input settings, and have a private, stable moment to review the decision. It may be less suitable for anyone who needs extensive explanations, live guidance, strong reassurance about repayment, or a workflow designed around assisted use. I would not recommend opening it for the first time during a crisis and immediately accepting the most prominent option.
The most inclusive way to use a cash-advance app is to slow down the decision even when the app is designed to move quickly. Enlarge the text if needed, reduce distractions, verify every field, and write down the repayment responsibility in words you understand. If another person helps you, keep ownership of the final review. Those steps make the experience more accessible without pretending that a digital interface can solve every financial or personal barrier.
My final recommendation is to treat Instant Cash Advance as an option to investigate, not a promise of effortless relief. It could be a practical fit for a short, specific cash gap and a user who values mobile convenience. Someone seeking ongoing money management, detailed human support, or a safer way to address recurring debt should look to a bank, budgeting service, credit counselor, or another alternative instead. The app’s strongest quality is its direct focus; its central weakness is that the urgency of that focus can encourage people to overlook the questions that matter most.
Gallery
Instant Cash Advance Pros and Cons
- Fast application process with quick eligibility decisions
- Useful for covering unexpected short-term expenses
- Simple interface makes borrowing details easy to review
- Repayment terms are presented clearly before acceptance
- May help users with limited traditional credit options
- Advance fees can make the total repayment expensive
- Late payments may lead to additional charges or penalties
- Approval and loan amounts vary by applicant and location
- Not suitable as a long-term solution for recurring expenses
- Requires sharing sensitive personal and financial information
Instant Cash Advance Frequently Asked Questions
What is Instant Cash Advance, and how does it work?
Instant Cash Advance is generally presented as a financial service or loan-matching app designed to help users request short-term funds through a mobile device. After entering personal, employment, income, and banking information, the service may evaluate the application and, in some cases, connect the user with a third-party lender. Approval, loan terms, and funding speed are not guaranteed and depend on eligibility and the participating provider.
Can I really receive money instantly after applying?
The word “instant” should be understood carefully. Although the application process may be completed quickly, approval and deposit times can vary considerably. Some users may receive a lending decision within minutes, while others may need to provide additional information or wait for verification. If approved, the money may arrive the same day or on the next business day, depending on the lender, bank, weekends, and holidays.
What fees and interest rates should I expect?
Before accepting any offer, review the annual percentage rate, interest charges, origination or administrative fees, late-payment penalties, and any optional services. Short-term cash advances can be expensive compared with traditional loans, and the final cost depends on the lender and your credit profile. Never rely only on promotional wording; read the complete repayment schedule and disclosure documents before agreeing.
What personal information does Instant Cash Advance require?
A cash advance application may request sensitive details such as your full name, address, date of birth, government identification number, employment information, income, bank account details, and contact information. Only submit data through the official app or a verified website, and check the privacy policy to understand how information is collected, shared, stored, and used by lending partners or marketing providers.
Is Instant Cash Advance safe and available to everyone?
Safety and eligibility depend on the specific app publisher, lender partners, and the country or state where you live. Check the developer identity, app-store reviews, permissions, privacy practices, customer support details, and licensing information before downloading. Applicants may also need to meet age, residency, income, bank-account, and employment requirements. Avoid services that guarantee approval, demand upfront payment, or pressure you to decide immediately.














